 Alloy
 ComplyAdvantage
 Feedzai
 Sumsub
 Persona
What is Sardine?
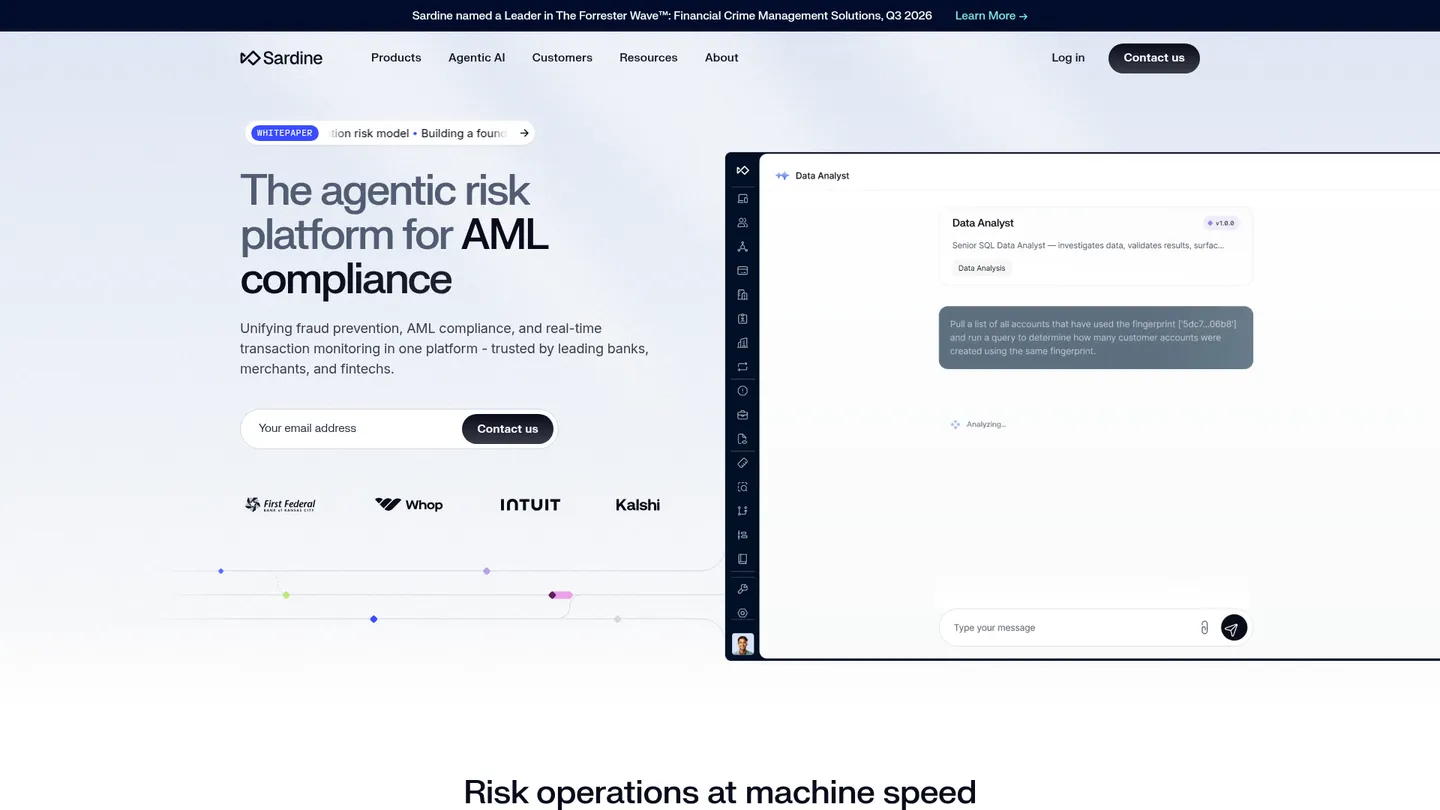
Sardine combines fraud prevention and financial-crime compliance. Its platform links device and behavioral intelligence, identity checks, transaction monitoring, and investigations.
Sardine is a cloud risk platform combining device intelligence, behavioral biometrics, identity data, transaction signals, and configurable rules for real-time fraud and compliance decisions. Customers can connect web, iOS, and Android SDKs and send account or transaction events through APIs. The platform returns risk signals and supports automated approval, decline, or review workflows for onboarding, payments, and account access. Analysts retain review control.
Coverage includes fraud prevention, device and behavioral intelligence, KYC and KYB, AML transaction monitoring, sanctions screening, case management, and SAR workflows. Sardine says its platform serves banks and merchants, and its 2026 positioning includes agentic AI for financial-crime operations. The breadth supports organizations consolidating point tools, while public materials do not provide a self-serve plan, rate card, or complete connector catalog.
Sardine uses a sales-led, usage-oriented enterprise model rather than published packages. Vendr reports a median buyer contract of $95,333 per year and a reported range of $15,000–$254,480, while Sardine does not publish those figures as list prices. A buyer may pay a minimum monthly commitment and draw down against platform, support, and consumption charges, with overages billed monthly. Pricing and implementation scope should be established in a quote.
Key features
Fraud decisioning
Combines device, behavioral, identity, network, and transaction signals with machine learning and configurable rules for real-time risk decisions.
Device intelligence
Uses device and behavioral signals to identify suspicious sessions, account takeover, bots, synthetic identities, and payment abuse.
Identity verification
Supports KYC and KYB workflows for verifying people and businesses during onboarding and ongoing risk operations.
AML monitoring
Provides transaction monitoring, sanctions screening, case management, and SAR filing workflows for financial-crime teams.
Risk orchestration
Lets teams route events to automated approval, decline, or manual review outcomes using custom thresholds and conditions.
Agentic operations
Positions AI agents as tools for automating fraud and AML operations across a unified financial-crime platform.
Developer integration
Offers web JavaScript, iOS, and Android SDKs plus REST APIs for submitting account, identity, and transaction events.
Sardine pricing
Sardine does not publish list prices or a public tier table. Vendr reports a median buyer contract of $95,333 per year and a $15,000–$254,480 range; its buyer note describes a minimum monthly commit, platform and support fees, consumption charges, and monthly overages. These are third-party benchmarks, not Sardine's published rates.
| Plan | Price | What's included |
|---|---|---|
| Enterprise platform | CustomUsage and implementation scope are quoted. | Fraud prevention, device and behavioral intelligence, identity verification, AML operations, APIs, SDKs, rules, and support |
Free trial: No public free trial or self-serve plan is listed.
Pros & cons
Pros
- Combines fraud, identity, device intelligence, and AML operations in one platform.
- Supports web and mobile SDKs plus REST APIs for real-time event processing.
- Configurable rules can route decisions to approval, decline, or manual review.
- Named customers include FIS, GoDaddy, Deel, Checkout, and Brex.
Cons
- Pricing is custom and Sardine does not publish a self-serve plan or rate card.
- The reported minimum-commit and overage model can make spend harder to forecast.
- A broad financial-crime suite may exceed the needs of simple, low-risk ecommerce use cases.
- Public materials do not provide a complete named integration catalog.
Who is Sardine best for?
- Fintechs and neobanks combining fraud prevention with AML and identity workflows.
- Banks and payments companies needing real-time risk decisions across onboarding and transactions.
- Crypto and digital-asset businesses managing identity, transaction, and financial-crime risk.
- Growing digital businesses supporting enterprise implementation and usage-based contracts.
Coverage
Integrations
Notable customers
Frequently asked questions
How much does Sardine cost?
+
Sardine does not publish list pricing or a public free plan. Vendr reports a median buyer contract of $95,333 per year and a reported range of $15,000–$254,480, with a minimum monthly commitment and usage-based charges described by a buyer.
How does Sardine work, and how long does implementation take?
+
Teams integrate Sardine's web or mobile SDKs and send account, identity, and transaction events through APIs. Sardine returns risk signals and supports rules-based outcomes, but it does not publish a standard implementation timeline. Timing depends on the workflows and data sources being deployed.
What does Sardine cover?
+
Sardine combines fraud prevention, device and behavioral intelligence, identity verification, AML monitoring, sanctions screening, case management, and SAR workflows. Teams can use these capabilities across onboarding, account access, payments, transactions, and financial-crime operations.
What integrations does Sardine support?
+
Public product materials identify a JavaScript web SDK, iOS SDK, Android SDK, and REST API. Sardine does not publish a complete named third-party connector catalog. Specific data, case-management, and payment integrations should be confirmed during procurement.
Who is Sardine for?
+
Sardine targets banks, fintechs, payments businesses, merchants, crypto companies, and other digital businesses managing fraud and financial crime. Publicly named customers include FIS, GoDaddy, Deel, Checkout, and Brex.
What supports Sardine's risk and compliance workflows?
+
Sardine combines machine-learning risk signals with configurable rules and review workflows. G2 reviewers rate it 4.8 out of 5 from 35 reviews. Buyers should request current security, data-processing, model-governance, explainability, and service-level documentation during diligence.
Sources
Facts and pricing verified on October 19, 2026. Vendors change pricing often, so confirm with Sardine before buying. How we research